Gap Insurance Cost Breakdown: Pricing, Depreciation Curves, and When Coverage Is Necessary
Understand how gap insurance premiums are calculated, compare dealership costs against auto insurance add-ons, and analyze vehicle depreciation curves to evaluate your financial risk.
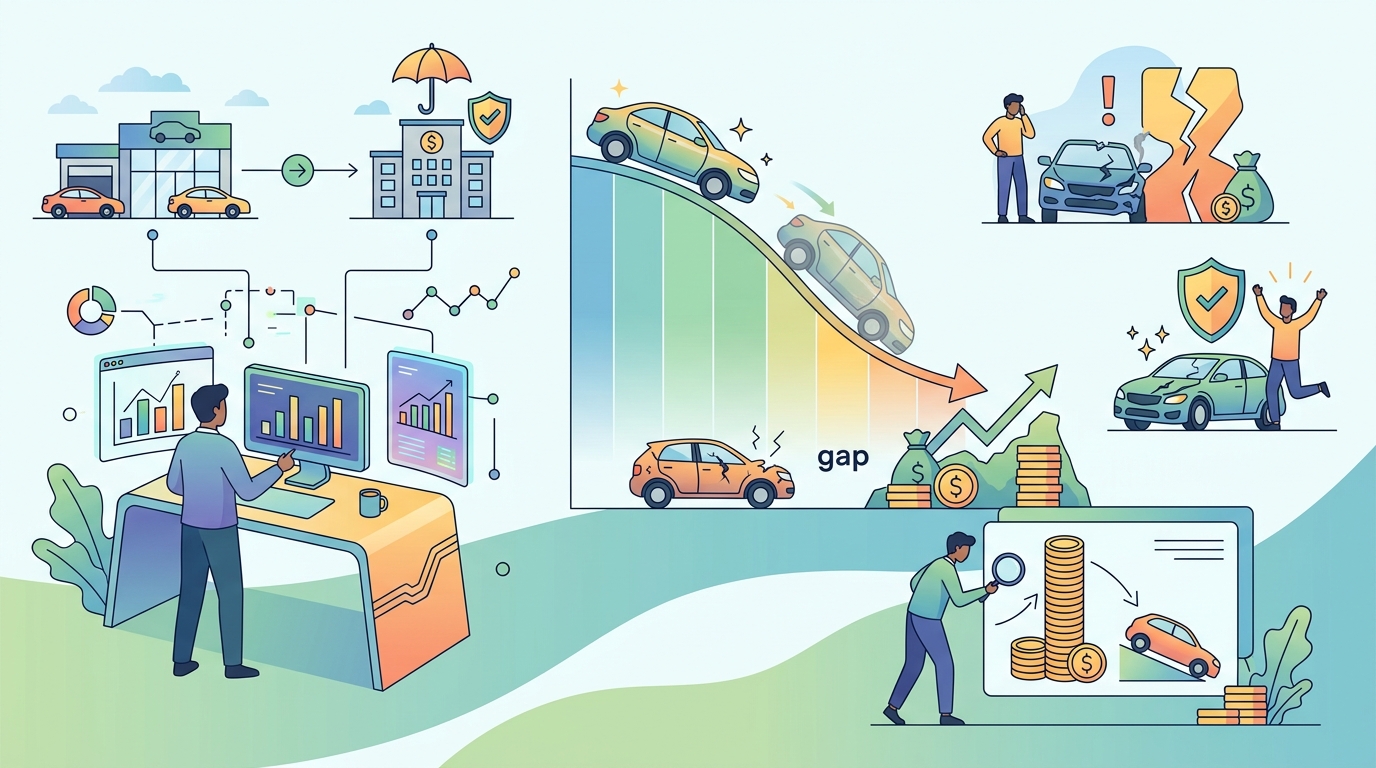
Understanding Gap Insurance Mechanics
When a vehicle is stolen or declared a total loss following an accident, standard auto insurance policies pay out based on the market value of the vehicle at that moment. This payout is known as the Actual Cash Value (ACV). However, if you financed or leased the vehicle, your remaining loan principal may exceed the ACV calculated by the primary insurer (Source 1). Guaranteed Asset Protection, commonly called gap insurance, is an optional financial product designed to cover this specific shortfall.
Without gap insurance, the vehicle owner remains personally responsible for paying the lender the difference between the primary insurance settlement and the outstanding balance of the auto loan (Source 1). This financial discrepancy arises primarily because vehicle market values decline rapidly during the first few years of ownership, whereas loan balances decrease according to a predetermined interest and principal amortization schedule.
How Gap Insurance Calculates the Coverage Gap
To evaluate whether you need gap insurance, you must understand how insurers and lenders quantify the coverage gap. The calculation relies on three main variables: the actual cash value determined by the primary insurance adjuster, your primary insurance deductible, and your remaining loan principal balance.
For instance, suppose a driver finances a vehicle for $36,000 with a small down payment. Twelve months later, an accident total-loss event occurs. The primary insurance company evaluates the car's market condition and sets the Actual Cash Value at $27,000. If the primary policy has a $500 deductible, the insurance payout to the lender is $26,500.
If the remaining principal balance on the loan is $32,000, the remaining debt after the primary settlement is $5,500 ($32,000 minus $26,500). A standard gap insurance policy pays this remaining balance directly to the financial institution, satisfying the borrower's obligation under the original auto loan contract (Source 1).
| Financial Variable | Example Dollar Amount | Explanation |
|---|---|---|
| Original Loan Balance | $36,000 | Total financed amount including vehicle cost, taxes, and fees. |
| Loan Principal at Month 12 | $32,000 | Remaining principal owed after 12 monthly payments. |
| Actual Cash Value (ACV) | $27,000 | Market value assessed by primary insurance adjuster at total loss. |
| Primary Policy Deductible | $500 | Amount subtracted from primary insurance payout. |
| Primary Insurance Payout | $26,500 | Net settlement paid to lender (ACV minus deductible). |
| Uncovered Gap Amount | $5,500 | Difference paid by gap insurance (or out-of-pocket if uninsured). |
New Vehicle Depreciation Curves and the Car Depreciation Loan Ratio
The primary driver of gap exposure is vehicle depreciation. According to consumer finance data and historical market trends, a brand-new vehicle typically loses between 15% and 20% of its market value within the first year of ownership (Source 1). Over the subsequent two to three years, depreciation generally continues at a rate of 10% to 15% annually.
The car depreciation loan ratio tracks how fast your loan principal declines relative to the market value of the vehicle. Long loan terms—such as 72 or 84 months—slow down principal reduction during the early years of the loan because a larger portion of each early monthly payment goes toward interest (Source 1). Consequently, long-term loans create a prolonged period where the loan balance exceeds the car's actual cash value.
| Ownership Timeline | Estimated Vehicle Depreciation | 60-Month Loan Principal Paid | 72-Month Loan Principal Paid | Typical Gap Status |
|---|---|---|---|---|
| Day 1 (Drive-off) | 90% of MSRP (10% drop) | 0% | 0% | High Gap Risk |
| Year 1 (Month 12) | 80% of MSRP (20% drop) | 15% | 11% | High Gap Risk |
| Year 2 (Month 24) | 70% of MSRP (30% drop) | 32% | 24% | Moderate Gap Risk |
| Year 3 (Month 36) | 60% of MSRP (40% drop) | 51% | 38% | Low/Moderate Gap Risk |
| Year 4 (Month 48) | 50% of MSRP (50% drop) | 73% | 56% | Equity Reached (No Gap) |
Cost Comparison: Auto Dealerships vs. Insurance Policy Add-Ons
Car buyers generally have two primary methods for purchasing gap insurance: acquiring a standalone policy through an auto dealership or adding a gap insurance endorsement (rider) to their existing auto insurance policy.
When purchased through a dealership, gap insurance is usually structured as a flat upfront fee, commonly ranging from $500 to $1,000. Dealerships frequently roll this cost directly into the overall auto financing package. When financed, the consumer pays interest on the gap insurance contract over the entire loan term, substantially increasing the effective gap insurance cost (Source 1).
Conversely, auto insurance providers typically sell gap coverage as an annual endorsement to a comprehensive and collision policy. This option generally costs between $20 and $60 per year ($2 to $5 per month). Adding gap coverage to an existing auto insurance policy allows the policyholder to cancel the coverage at any point once the vehicle's loan balance equals or falls below its actual cash value.
| Purchase Channel | Average Total Cost | Payment Method | Financing Interest Applied? | Cancellation Flexibility |
|---|---|---|---|---|
| Auto Dealership | $500 – $1,000+ | Upfront lump sum or financed in loan | Yes (if rolled into financing) | Requires formal refund application |
| Auto Insurance Company | $20 – $60 per year | Added to monthly auto premium | No interest charges | Can drop coverage at any time |
Loan-to-Value (LTV) Scenarios: Mandatory vs. Redundant Coverage
The ratio of your initial loan amount to the vehicle's retail price (Loan-to-Value ratio, or LTV) is the primary indicator of whether gap insurance is necessary. High LTV scenarios create immediate financial exposure, while low LTV scenarios render gap insurance redundant.
Scenarios Where Gap Coverage Is Mandatory or Highly Recommended
- Auto Lease Agreements: Auto lease gap insurance coverage is frequently mandatory. Most leasing companies require gap coverage to protect their asset, and many automatically include it within the standard lease contract agreement.
- Small or Zero Down Payments: Financing a vehicle with less than 10% to 20% cash down creates an initial LTV near or above 100% when taxes, registration fees, and dealer fees are included (Source 1).
- Extended Loan Terms: Loan terms extending to 60, 72, or 84 months lower monthly payments but slow down principal accumulation, extending the length of time your loan balance remains higher than the vehicle market value (Source 1).
- Negative Equity Rollovers: Rolling over unpaid balances from a previous car loan into a new auto loan increases the initial balance far past the true market value of the new car.
Scenarios Where Gap Coverage Is Redundant
- Substantial Down Payments: Putting down 20% or more in cash ensures that the initial loan balance is lower than the car's immediate actual cash value.
- Short-Term Loans: Financing over 36 to 48 months accelerates principal repayment, allowing the loan balance to drop faster than typical vehicle depreciation curves.
- High Equity Status: Once a borrower pays down the principal balance to a point where the car's resale value comfortably exceeds the remaining debt, maintaining gap insurance provides no financial benefit.
Refinancing Impact on Existing Gap Coverage Policies
Refinancing an auto loan replaces the original loan contract with a completely new loan agreement. Because dealership gap insurance contracts are tied directly to the specific original financing agreement, refinancing automatically terminates the coverage under that original gap policy (Source 1).
When refinancing a loan that includes a dealership-purchased gap policy, borrowers should contact the original gap provider or dealership to request a prorated refund for the unused term. Failing to request this refund means paying for coverage that is no longer legally active.
If the loan balance on the refinanced agreement still exceeds the vehicle's market value, the borrower must purchase a new gap insurance policy or add a gap rider through their auto insurer to maintain protection under the new loan structure (Source 1).
How to Evaluate Your Gap Risk Step-by-Step
Before deciding whether to purchase or drop gap insurance, perform a quick financial assessment using these steps:
- Check Your Current Balance: Look up your latest payoff balance from your auto lender statement.
- Determine Actual Cash Value: Estimate your car's private-party or trade-in value using independent pricing guides and market valuation tools.
- Subtract Value from Loan Balance: If your payoff balance is higher than the estimated market value, that difference is your gap exposure.
- Compare Insurance Premiums: Check if your existing vehicle insurance company offers a gap rider before agreeing to dealership contract additions.
Do I need gap insurance if I put 20% down on a new car?
A 20% down payment usually creates enough initial equity to offset early vehicle depreciation. In most cases, putting 20% down prevents the loan balance from exceeding the car's actual cash value, making gap insurance unnecessary.
How does auto lease gap insurance coverage work compared to purchase financing?
Auto lease contracts frequently incorporate gap coverage into the standard lease agreement automatically. For financed vehicle purchases, gap insurance must usually be purchased separately as an insurance rider or finance contract add-on.
Can I cancel gap insurance once my car depreciation loan ratio balances out?
Yes. If you purchased gap coverage as an add-on through your primary auto insurer, you can remove the rider at any time once your loan principal is less than the vehicle's market value. If bought as a lump-sum contract through a dealership, you can request a prorated refund for the unused term.
Sources
- Auto Loan Resources — Consumer Financial Protection Bureau
This article is for general information only and is not professional advice. Figures come from public sources and change over time; check the official source before you act.
More from Inside Life Digest
- Gap Insurance Cost Breakdown: Pricing, Depreciation Curves, and When Coverage Is Necessary
- Long-Term Care Insurance Cost Breakdown: Premiums, Elimination Periods, and Benefit Triggers
- Evaluating Private Student Loan Refinancing: Interest Rate Mechanics, Federal Protection Losses, and Savings Calculus
- Comprehensive Travel Insurance: Medical Evacuation, Cancellation, and Pre-Existing Condition Waivers
- Revocable Living Trust vs. Will: Cost, Probate Avoidance, and Asset Transfer Rules
- Cyber Insurance Requirements for Small Businesses: Coverage Limits and Underwriting Criteria